
The art of selection.
Every property shown here has been visited and chosen by a broker. We look at the location, how it lives and the price before we show it.
Not everything goes through the catalogue.
The finest sales are often concluded without an advert, between people who trust each other. Le Cercle was born of that reality. Stéphane Blatti explains why in his letter.

Catalogue of properties for sale
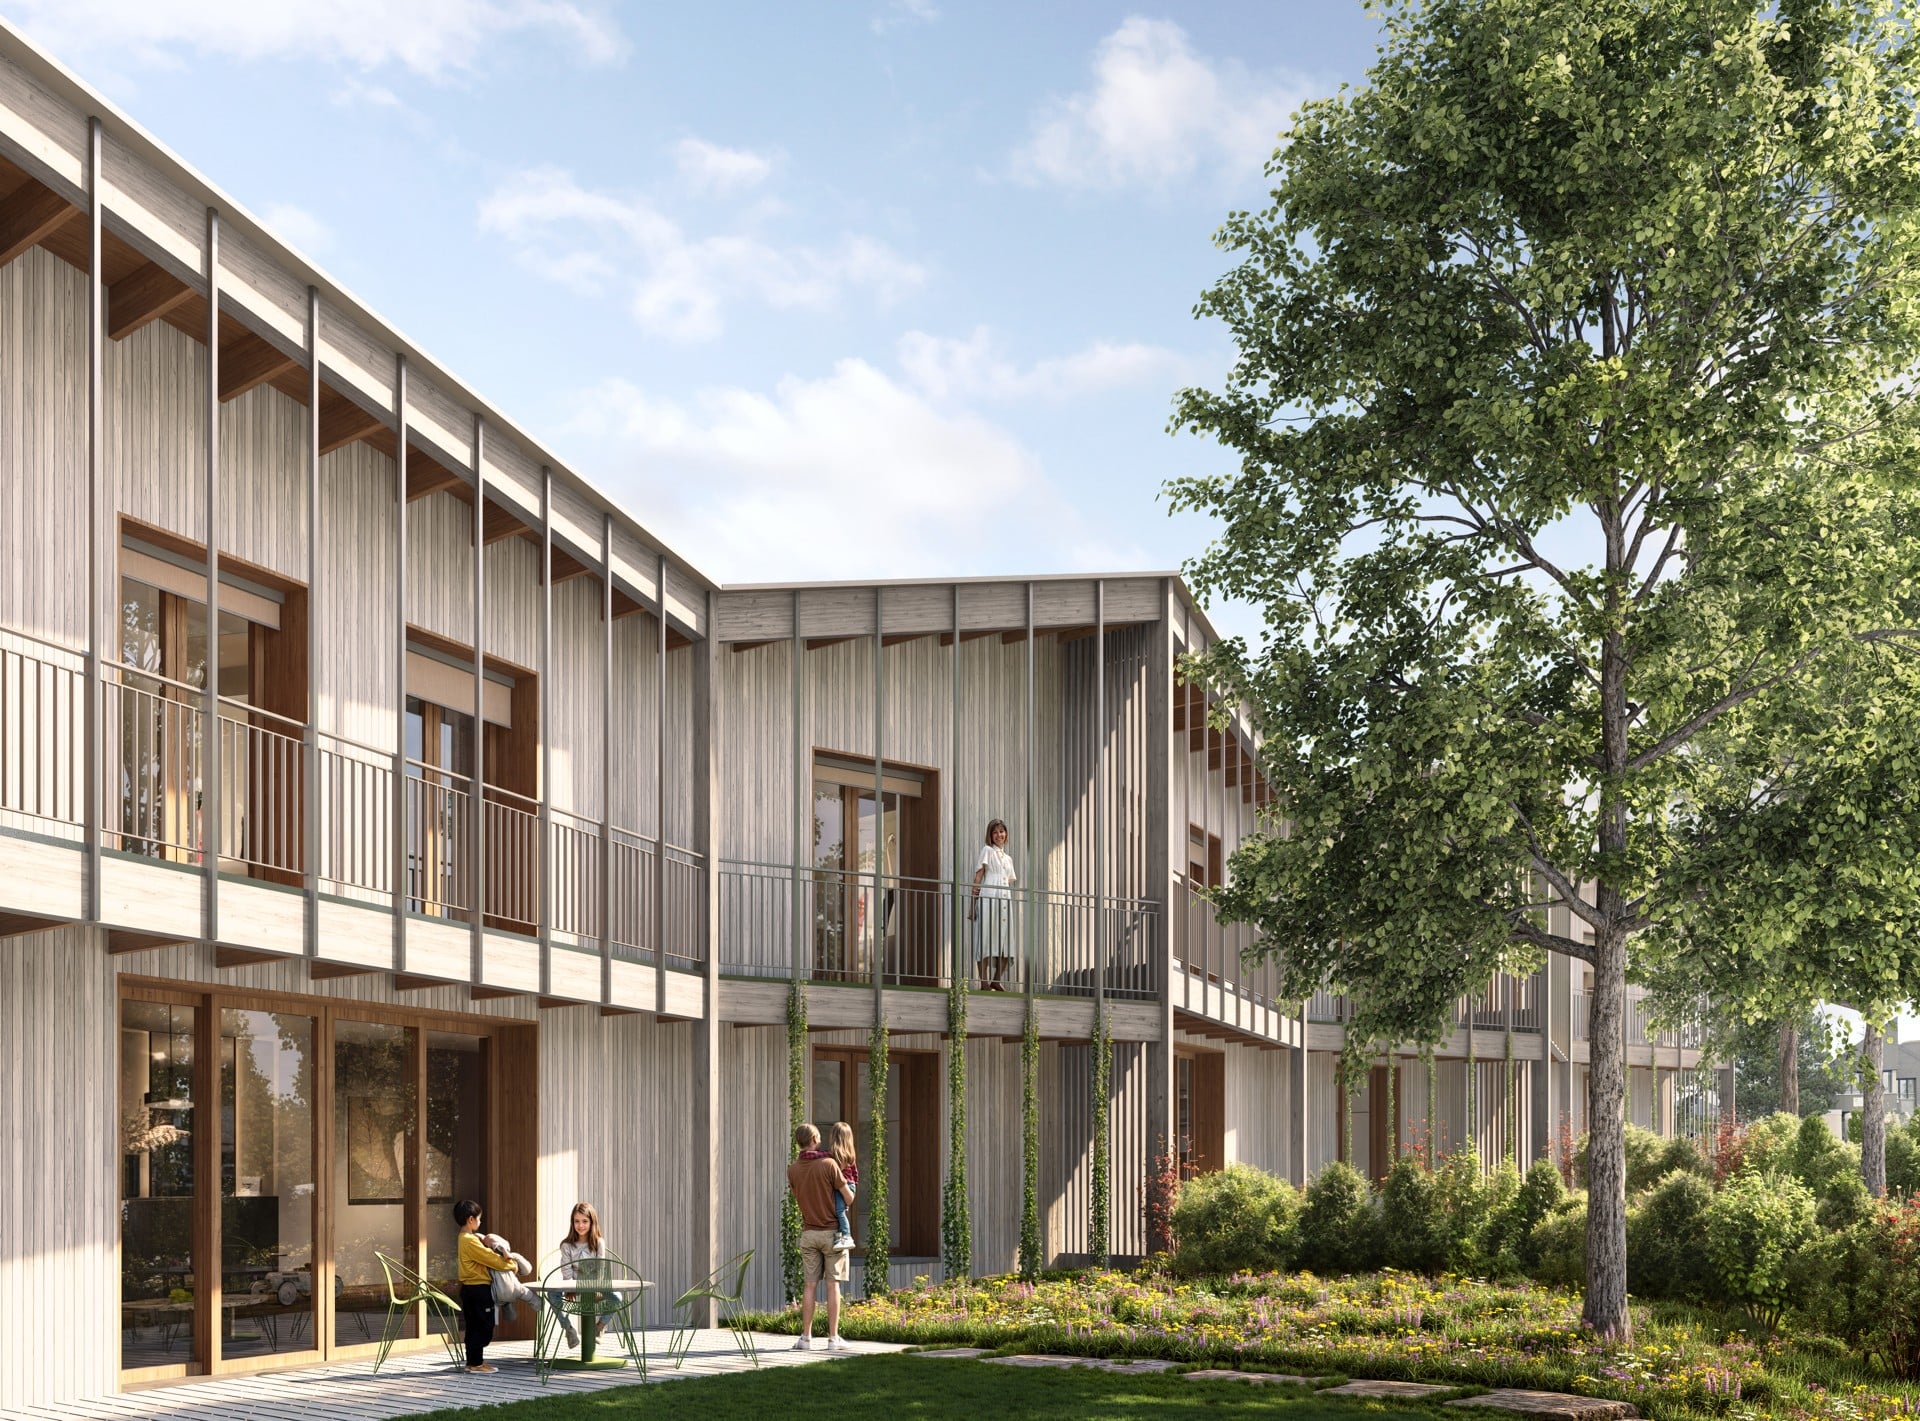
Domaine des Courbes, six new villas by the lake.
Two semi-detached villas and four triplexes, delivery planned for the second half of 2028. Marketed by CI-Léman, price on request.
Signature editions.
Developments that developers entrust to us, presented to our clients fifteen days before the market. A complete file, a dedicated broker, viewings by appointment.
Every property visited first
We visit each property before you, and tell you what a listing leaves unsaid.
Complete file delivered
Professional photos, drone, 2D and 3D plans, Matterport for the properties that lend themselves to it.
Accompanied viewings
Your dedicated broker welcomes you personally, from the first contact to the signing.
Off-market, by introduction
Some of our properties are never listed. We present them discreetly to qualified buyers.
What the buyers we supported say
M. Chandy a été très efficace et disponible pour nous accompagner dans notre réflexion quant à l’achat d’un appartement! Merci!
Nous remercions Monsieur Billaux dans son accompagnement pour l'achat de notre maison. Il s'est montré très professionnel et sympathique. Nous avons également beaucoup apprécié sa disponibilité pour répondre à toutes nos questions. Nous recommandons monsieur Billaux pour votre acquisition immobilière.
Nous avons eu le plaisir d'être accompagnés par Monsieur Cimorelli tout au long de notre processus d'achat immobilier, et nous ne pourrions pas être plus satisfaits. Malgré quelques soucis externes, Monsieur Cimorelli a su nous guider avec professionnalisme, patience et expertise. Son soutien constant et ses conseils avisés ont été précieux à chaque étape. Nous recommandons vivement ses services à quiconque recherche un conseiller immobilier de confiance.
Buyers' questions
How much can you borrow in Geneva?
Banks apply two rules. Equity first: at least 20% of the price. Affordability next: the theoretical costs of the property (interest calculated at a rate of about 5%, amortisation and maintenance) must not exceed one third of your gross income. In practice, a household can aim for a purchase price of about five times its gross annual income: with CHF 150'000 of income, a property of around CHF 800'000. The precise calculation is done with the bank or a financing specialist, before viewings, not after.Source : Bank lending guidelines (theoretical rate, affordability).
What total budget should you plan beyond the purchase price in Geneva?
Beyond the price, allow about 4% in acquisition costs (3% registration duty, land register and notary) and, if you borrow, the mortgage certificate (cédule hypothécaire), around 2.5% of its amount. You also need at least 20% equity. Casatax can reduce the duties for an eligible main residence. Example for a CHF 1'000'000 property: about CHF 40'000 in acquisition costs and CHF 20'000 for the mortgage certificate (a CHF 800'000 loan), on top of CHF 200'000 of equity. For a main residence eligible for Casatax: the duties fall by about CHF 21'000 and the mortgage certificate costs by half. Total costs drop from about CHF 60'000 to CHF 29'000.Source : notaires-geneve.ch, ge.ch (2026 scales).
How much equity do you need, and can you use your pension fund (2nd pillar)?
Allow 20% of the purchase price in equity, of which at least 10% must come from a source other than the pension fund: savings, 3rd pillar, a gift or an advance on inheritance. The 2nd pillar can top this up, through early withdrawal or pledging (pledging preserves your pension but requires a higher income). On top of this come the acquisition costs, about 4%, payable in cash. Each structure is put together with the bank, before making an offer.Source : Banks · BVG/LPP provisions (home ownership promotion).
What is Casatax, and are you entitled to it?
Casatax is a Geneva reduction of registration duties for the purchase of a main residence. 2026 scales: a reduction of up to CHF 20'924 if the property price does not exceed CHF 1'394'928, plus a halving of the costs linked to the mortgage certificate. Conditions: be a private individual, occupy the home within two years of purchase, and keep it as a main residence for at least three years. The amounts are indexed every March.Source : ge.ch (2026 scales).
Should you choose a fixed-rate or SARON mortgage in Geneva?
A fixed rate guarantees a stable monthly payment over the chosen term. SARON follows the money market: often cheaper, but variable. Our recommendation, tested with our buyers: do not put all your eggs in one basket. Splitting the loan into tranches (one part SARON, one at 5 years, one at 7 years, one at 10 years) smooths the maturities: you never renew the whole loan at the same time, at a rate that could be higher. The final decision is made with your bank or financing specialist, according to your horizon and risk tolerance.Source : Swiss National Bank (SARON) · mortgage financing practice.
What is the imputed rental value and how is it taxed in Geneva?
The imputed rental value (valeur locative) is notional income attributed to owners who live in their property, added to their taxable income; in return, mortgage interest and maintenance costs are deductible. Its abolition was approved in a federal vote on 28 September 2025 and will take effect on 1 January 2029. Until then, it remains taxable.Source : admin.ch (Federal Department of Finance), AFC-GE.
Can you buy a property before selling your current one in Geneva?
Yes, we handle this every month. In Geneva, properties are scarce: our clients sell and search at the same time, and the order of the two cannot always be chosen. The bank bridges the gap with bridging finance (also called a bridging loan), repaid at the notary's as soon as the sale completes. How long it lasts depends on a single variable: the price. A property valued at its fair market price generally sells in three months. Everything therefore starts with the valuation. In twenty years of chained sales, we have always found a solution. Speak to a broker before committing: a valuation is confidential, with no obligation.Should you buy a condominium apartment (PPE) or a house in Geneva?
It is not just a question of budget, it is a question of life stage. Many of our clients already own a house: with the children gone, it becomes too big, and an apartment makes perfect sense. You turn the key and travel with peace of mind. An apartment can also be a pied-à-terre in Geneva. Other families want to create their own setting, house or apartment, already built or off-plan: we support them there too. A house requires constant upkeep, a different philosophy of life. A condominium apartment involves co-ownership (shared charges, renovation fund, regulations), but also its lightness. In Geneva, houses are rarer, and therefore more sought after, and several of the projects developers entrust to us are not yet on the market. Our registered clients receive each new development first, fifteen days before it opens to the market. Now is the right time to sign up. Everything depends on your way of life, and we are here to help you see clearly, even before you start searching.What are an owner's running costs in Geneva?
Beyond the mortgage, an owner bears maintenance, building insurance, the supplementary property tax and, if they live in the property, the imputed rental value added to their taxable income (until the end of 2028). In a condominium, co-ownership charges are added. In practice, allow about 1% of the property's value per year, all in. Our advice to owners who are keeping their property: maintenance works (those that preserve value, as opposed to value-adding works) are currently deductible from taxable income, and this deduction will disappear with the imputed rental value at the end of 2028. Until then, a tax window is open: plan your renovations now.Source : ge.ch, AFC-GE · imputed rental value reform (in force 1.1.2029).
How long does a property purchase take in Geneva?
For an existing property, it can be quick: sometimes a few days, when the buyer's financing is already in place. As a rule, allow several weeks between the accepted offer and the notarial deed: this is the time needed for the financing and the bank's approval. The steps then follow naturally: offer, agreement between the parties, file at the notary's, signing and entry in the land register.Source : notaires-geneve.ch.
Who can buy in Geneva, depending on their permit?
More people than you might think. An EU/EFTA national resident in Switzerland (B or C permit) buys freely, like a Swiss citizen. So does a third-country national with a C permit. With a B permit, a third-country national may acquire, without authorisation, the main residence they occupy themselves. An EU/EFTA cross-border commuter (G permit) may buy a secondary residence near their place of work, occupied personally and never rented out. Only people domiciled abroad fall fully under the Lex Koller, with its very restrictive regime. Financing depends on each bank (equity, income, exchange-rate risk for income in euros) and should be framed well in advance.Source : BewG/LFAIE (bj.admin.ch) · Geneva Chamber of Notaries · banks.
Does using an agency cost the buyer anything?
No. In Geneva, the brokerage commission is paid by the seller who granted the mandate. For you, the buyer, our support costs nothing: viewings, full documentation, introductions for financing and follow-up through to the deed are included. You can also give a broker a search mandate: this is a paid service, whose terms are agreed together, before any steps are taken.Source : Geneva brokerage practice.
Which documents should you check before buying a condominium apartment (PPE)?
Ask for the condominium regulations, the allocation schedule, the list of easements, and the minutes of the last three general meetings: they tell you about the life of the building (works approved, any disputes, upcoming expenses). Add the service charge statements, the status of the renovation fund and your share in thousandths. These documents should be read before making an offer.Source : ge.ch (condominium ownership).
Offer to purchase, promise of sale, forward sale: how do you commit in Geneva?
An offer to purchase tells the owner you want to acquire their property and opens the negotiation: several exchanges may follow, until agreement. At this stage, you are not yet definitively bound. Then comes the commitment at the notary's, in one of three forms depending on your situation. A direct sale: the deed is signed and executed. A forward sale: you sign now, the transfer and payment take place on an agreed date, and your right is noted in the land register. A promise of sale: a notarial deed binding both parties, often with a deposit, before the final deed. Worth knowing: a promise involves two visits to the notary, and therefore higher costs; a direct or forward sale locks in your purchase definitively in a single deed, at lower cost. The right structure depends on your situation (financing to finalise, chained sale, off-plan property) and is chosen with the notary and your broker. The notaires-geneve.ch website details each of these forms.Source : notaires-geneve.ch · CI-Léman, Geneva practice.
Can you buy a property in Geneva through a company?
It is possible, but the Lex Koller applies according to the shareholding: a company controlled from abroad may require authorisation. The taxation differs from a purchase in your own name, and Casatax is reserved for private individuals. This choice should be weighed with a notary and a tax adviser.Source : bj.admin.ch, ge.ch.
Describe the property you are looking for,
we will find it.
We first qualify your project, then present the properties that match, including off-market.